Apple Inc. is planning a 4-for-1 stock split and it has important implications for the Dow Jones Industrial Average, of which it is a key component.
The iPhone maker on Thursday announced that its board approved the stock split. The split, intended to make Apple “more accessible to a broader base of investors,” will impact owners of record as of Aug. 24 and Apple’s shares AAPL,
+1.21%,
which closed at $384.76 on Thursday, will trade on a split-adjusted basis on Aug. 31.
Because the Dow DJIA,
-0.85%
is a price-weighted index, the scheduled split at the end of next month means that Apple will move from the most influential component of the 30-member blue-chip index to perhaps the 15th- or 16th-most significant member of the index.
The Dow’s price-weighting means the value of the stock gauge is determined by the price changes of its components, rather than percentage changes. The overall value of the index is computed by adding the price of the components and dividing by the so-called Dow divisor, which currently stands at 0.14744568353097.
That means that every dollar move of a company translates to a 6.78-point swing in the 124-year-old benchmark.
The divisor accounts for stock splits, so in that way Apple’s 4-for-1 split will alter its own influence on the benchmark and the divisor by which the index is calculated. The divisor is determined by S&P Dow Jones Indices, which owns the Dow indexes.
UnitedHealth Group Inc. UNH,
-0.47%,
which closed at $305.23, could become the most influential member of the Dow at the end of August. Home Depot Inc. HD,
+0.62%
is currently the third-priciest stock in the Dow, finishing Thursday trade at $266.31.
Apple has been the largest, and therefore the most influential, Dow component since April 29, according to Dow Jones Market Data.
Other indexes, including the S&P 500 index SPX,
-0.37%
and the Nasdaq Composite Index COMP,
+0.42%,
are market-capitalization weighted, therefore they are impacted by the overall value of their components.
Apple currently stands as the biggest company by market cap, boasting a value of $1.647 trillion, as of Thursday’s close, according to FactSet data. Microsoft MSFT,
-0.07%
ranks No. 2 at $1.54 trillion, while Amazon.com Inc AMZN,
+0.60%
is the third-most highly valued U.S. company at $1.513 trillion.
It is for that reason that the large-capitalization components have had an outsize impact on returns for the broader market, excluding the Dow, since stocks hit their recent nadir in late March.
For example, the price-weighted Dow has gained 41.5% since its March 23 low, while the S&P 500 has returned 45% and the Nasdaq has climbed 54% over the same period.
Apple became a Dow member back in March 2015. Back then, AT&T T,
+0.03%
was taken out in exchange for the Cupertino, Calif.-based technology behemoth.
Splits of shares in Dow components aren’t uncommon. Nike Inc. NKE,
-0.15%
announced a 2-for-1 stock split back in December 2015.
Apple’s stock-split announcement came after the company brushed off the COVID-19 crisis to report record results Thursday. The company posted fiscal third-quarter net income of $11.25 billion, or $2.58 a share, up from $10.04 billion, or $2.18 a share, in the year-prior quarter. Analysts surveyed by FactSet had been anticipating $2.05 a share.
CNBC’s Jim Cramer on Thursday reacted to the quarterly reports that four of the five largest publicly traded companies posted after markets closed.
Shares of Amazon, Apple, Facebook and Alphabet, with a combined market value of more than $4.8 trillion as of Thursday’s close, are all up in the aftermarket after each company topped Wall Street estimates in a quarter consumed by the coronavirus pandemic that has disrupted global economies.
“These big tech stocks have been roaring because they either benefit directly from the pandemic or they’ve figured out how to thrive in spite of it,” the “Mad Money” host said.
One day prior, the chief executives of each tech titan were summoned before Congress to testify on antitrust claims. Cramer called the House antitrust subcommittee the “greatest stock-picking research firm in the world” after lawmakers on both sides of the aisle grilled the company heads on their business practices and outsized dominance in their respective markets.
“When I’m searching for long-term investments,” Cramer said, “I dream of finding companies that [are] so powerful [and] so strong, that they end up being hauled in front of Congress for destroying their competition fair and square.”
Amazon
Amazon shares surged more than 5% in the aftermarket after the e-commerce giant reported earnings of $10.30 per share on revenue of $88.91 billion, well above the $1.46 per share and $81.56 billion numbers, respectively, analysts were looking for.
“They weren’t even trying to have an incredibly profitable quarter. They spent aggressively to build capacity for the stay-at-home economy, and to keep their employees safe,” Cramer said. “As for the next quarter, Amazon gave you a blowout forecast. The stock’s on fire.”
Apple
Apple stock shot up about 6% after posting a blockbuster report and announcing a four-for-one stock split after the bell. The company recorded $59.69 billion on the top line, compared to analyst estimates of $52.25 billion, and $2.58 per share on the bottom line, a 54-cent beat.
“While Apple didn’t give us a forecast for the next quarter, they did give us … a four-for-one stock split, which should make this one a lot more enticing to home-gamers who might be scared away from a $400-plus price tag,” the host said. “Many other companies should actually watch what [CEO] Tim Cook does here and stop watching what Warren Buffett does. Do what Tim Cook does. It’s another reason why Apple is zooming after hours.”
Facebook
Shares of Facebook rallied above 6% after besting analyst estimates in the second quarter. The social media giant reported earnings of $1.80 per share, when Wall Street was looking for $1.39, on revenues o $18.69 billion, more than $1 billion above expectations.
“After all the sturm und drang about major advertisers boycotting the platform, Facebook shot the lights out,” Cramer said. “Even better, July’s going strong. Millions of small businesses need Facebook. Instagram Shops is a gigantic hit. This is a small- and medium-sized business juggernaut. No wonder the stock’s flying in after-hours trading.”
Alphabet
Google-parent Alphabet is the laggard here with its stock up less than 1% in extended trading. The online behemoth beat on the top and bottom lines, but the company saw revenues decline for the first time in its history. Alphabet brought in $38.30 billion in revenue and produced profits of $10.13 per share, while analysts predicted $37.37 billion and $8.21, respectively.
“Their numbers were substantially better than expected, even as their core advertising business took a major hit,” the former hedge fund manager said. “The stock barely budged in response, but I think that’s because Alphabet’s management is so non-promotional.”
Disclosure: Cramer’s charitable trust owns shares of Amazon, Alphabet, Apple and Facebook.
Rep. Pramila Jayapal during the House Judiciary Subcommittee on Antitrust, Commercial and Administrative Law on July 29. MANDEL NGAN/Getty Images
Rep. Pramila Jayapal is on a roll. Over the past two days, the Democrat from Washington has orchestrated two of the most memorable exchanges in two separate House hearings. In the first, she exposed the naked racism and political motivations behind Attorney General William Barr’s attacks on Portland protesters. In the second, she all but caught Facebook CEO Mark Zuckerberg in a series of lies about Facebook’s business practices.
During Jayapal’s questioning of Barr on Tuesday, the attorney general tried to dispute that law enforcement officers used tear gas to disperse protesters for the president’s photo op near Lafayette Square in June. Officials have admitted to using chemical eye irritants in the attack on demonstrators, but, Barr said on Tuesday, “tear gas is a particular compound” that was not used. Jayapal stood firm. “I’m starting to lose my temper,” she told him, after he refused to address the substance of the question for the third or fourth time.
Barr also attempted to defend the deployment of federal agents to quash racial justice protests in Portland under the guise of protecting a federal building. Meanwhile, he denied ever hearing about the armed protesters in Michigan who, demanding an end to stay-at-home orders, stormed the state capitol and threatened to lynch Gov. Gretchen Whitmer in May. Jayapal pointed out the disparity in his responses to these two groups of demonstrators. When Barr tried to interrupt her to say he only cared about protests that affect federal property, Jayapal cut him off. “This is my time, and I control it,” she said. She went on:
When protesters carry guns and Confederate flags and Swastikas and call for the governor of Michigan to be beheaded and shot and lynched, somehow you’re not aware of that … because they’re getting the president’s personal agenda done. But when black people and people of color protest police brutality, systemic racism, and the president’s very own lack of response to those critical issues, then you forcibly remove them with armed federal officers, pepper bombs, because they are considered terrorists by the president.
Unlike her Democratic colleagues, who effectively questioned Barr on racism within police forces and his fear-mongering around mail-in voting, Jayapal didn’t get Barr on the record with any particularly damning statements. But her line of questioning offered more than just the hollow satisfaction of a good burn and the pleasure of watching a righteous legislator exert her power over a man who routinely abuses his. Most people don’t have the time or inclination to watch lengthy Congressional hearings. If there’s big news, they’ll read the headlines or watch clips on their nightly news shows, but much of the substance of these hearings often goes unnoticed. By reacting to Barr’s outrageous deflections with the outrage they warranted, Jayapal ensured she’d make headlines. Then, she gave viewers and readers a concrete example of the Trump administration’s racist hypocrisy, in bracingly clear language. Unlike Democratic presidential candidate Joe Biden, who said in an address on Tuesday that “anarchists should be prosecuted”—leading some progressives to argue that Trump and Biden are “two sides of the same coin”—Jayapal made no mealy-mouthed qualifications. She focused the blame where it belonged: not on political dissidents, but on state entities that are violently attempting to suppress them.
Her line of questioning offered more than just the hollow satisfaction of a goodburn.
On Wednesday, Jayapal emerged in the spotlight again. The House Judiciary’s antitrust subcommittee convened the giants of the tech world—Zuckerberg, Amazon’s Jeff Bezos, Google’s Sundar Pichai, and Apple’s Tim Cook—to answer questions about their anticompetitive business practices. Jayapal began her Zuckerberg interrogation by quoting emails and statements from multiple Facebook executives, including the CEO himself, who’ve said that Facebook should block competitors from gaining traction in the marketplace and copy their products if necessary. Then, she asked him, “Has Facebook ever taken steps to prevent competitors from getting footholds by copying competitors?”
Zuckerberg dodged. So she rephrased: “Since March of 2012, after that email conversation, how many competitors did Facebook end up copying?” “Congresswoman, I—I can’t give you a number of companies,” Zuckerberg replied.
After Zuckerberg said he didn’t remember any conversations in which he’d threatened to copy competitors’ products if they didn’t let Facebook acquire their businesses, Jayapal read aloud quotes from an online chat transcript that showed Zuckerberg doing exactly that, in conversation with Instagram’s founder. “Facebook is a case study, in my opinion, in monopoly power, because your company harvests and monetizes our data and then your company uses that data to spy on competitors and to copy acquire and kill rivals,” Jayapal said. “These tactics reinforce Facebook’s dominance, which you then use in increasingly destructive ways.”
These hearings aren’t trials. In some cases, their public value is largely theatrical: The bigshots who are called to testify hedge and stall, while the members of Congress pontificate from their seats, putting on a show for their constituents. Wednesday’s hearing fit this mold. The antitrust subcommittee had already been investigating these companies for more than a year, conducting hundreds of hours of interviews and collecting more than 1 million documents. At the hearing, the members didn’t extract much new information. Their main job was to make public the information they already had—and to make their constituents care. And Jayapal has proven herself to be remarkably skilled at merging performance with substance.
If there was ever any illusion that elected officials in this pseudo-democracy could be trusted to uphold the laws that govern it, the events of the past few years should have extinguished that hope. Powerful corporations and politicians will not police themselves, and many members of Congress will not risk angering the donor class unless there’s a public outcry to justify it. Jayapal didn’t just catch Zuckerberg in a defensive posture about Facebook’s unjustifiable consolidation of power in the tech industry. She laid the groundwork for the rest of America to understand what Facebook has been doing, grasp the cynicism of Zuckerberg’s attempted self-exoneration, and connect the dots between Facebook’s anticompetitive strategies and its role in the erosion of American democracy. If Congressional Democrats ever hope to build popular support for breaking up or imposing stricter regulations on monopolies like Facebook, they’ll need people like Jayapal—who represents a district where many Amazon employees live—to sell the public on the urgency of the issue.
There is great value in confronting abuses of power directly, in public view, with suchclarity.
Jayapal’s week of scorchings comes on the heels of another notable show of strength in the House. Last week, Rep. Alexandria Ocasio-Cortez stood on the House floor and addressed her Republican colleague, Rep. Ted Yoho, who’d called her a “fucking bitch” in front of an audience of reporters. She got a lot of approving (and deserved) press coverage of her speech, in which she laid into Republicans who’ve used their wives and daughters as shields against allegations of misogyny. Some would dismiss quotable, passionate, made-for-TV addresses like hers—and heated exchanges like Jayapal’s—as sound-bitey clapbacks with little concrete political import. But there is great value in confronting abuses of power directly, in public view, with such clarity. It gives people who haven’t been paying much attention an accessible explanation for why they should be worked up and the language they need to explain it to others.
It also gives many of us a worthy proxy for our impotent anger, transforming feelings of powerlessness into those of power. Yoho insists he said bullshit, not bitch, and besides, he says, Ocasio-Cortez deserved it; Zuckerberg insists that the threat he delivered to Instagram was no threat at all. It’s enough to make any rational, incensed observer wonder if she’s going mad—and yet, here are two members of Congress who firmly assure her she’s not. It is a formidable prophylactic against political apathy to see one’s fury at seemingly unchecked injustices expressed on a public stage by an elected official. It’s representative democracy at work.
Readers like you make our work possible. Help us continue to provide the reporting, commentary, and criticism you won’t find anywhere else.
LIKE MOST international jamborees these days the Farnborough air show wrapped up on July 24th as a virtual event. Webinars featuring grim-faced executives were not as entertaining as noisy acrobatic displays by fighter jets. But commercial aviation’s most important showcase at least marked a point when heads began to turn away from the devastation wrought by covid-19 and towards what comes next.
As airlines sell fewer tickets, owing to pandemic travel restrictions or travellers’ fear of infection, the industry that makes flying possible faces a reckoning. Aircraft-makers will make fewer passenger jets and so need fewer parts from their suppliers. Ticket-sellers will see less custom and airport operators, lower footfall. Many firms have cut output and laid off thousands of workers. The question now is how far they will fall, how quickly they can recover, and what will be the long-lasting effects.
The airline-industrial complex is vast. Last year 4.5bn passengers buckled up for take-off. Over 100,000 commercial flights a day filled the skies. These journeys supported 10m jobs directly, according to the Air Transport Action Group, a trade body: 6m at airports, including staff of shops and cafés, luggage handlers, cooks of in-flight meals and the like; 2.7m airline workers; and 1.2m people in planemaking. In 2019 they helped generate revenues of $170bn for the world’s airports and $838bn for airlines. Airbus and Boeing, the duopoly atop the aircraft supply chain, had sales of $100bn between them. For the aerospace industry as a whole they were perhaps $600bn. Add travel firms like Booking Holdings, Expedia and Trip.com, and you get annual revenues of some $1.3trn in normal times for listed firms alone, supporting roughly as much in market capitalisation before covid-19—and rising.
Taxiing times
Instead, the coronavirus has lopped $460bn from this market value (see chart 1). Airline bosses are reassessing trends in passenger numbers, which had been expected to double in the next 15 years, just as they had with metronomic regularity since 1988, despite blips after the 9/11 terrorist attacks of 2001 and the financial crisis of 2007-09. Rather than increase by 4% this year, air-transport revenues will fall by 50%, to $419bn. After ten years of unusual profitability the $100bn of total losses forecast for the next two years is equal to half the nominal net profits the industry raked in since the second world war, calculates Aviation Strategy, a consultancy. Luis Felipe de Oliveira, director-general of ACI World, which represents the world’s airports, gloomily predicts that revenues there will fall by 57% in 2020.
Despite signs of life, particularly on domestic routes in large markets like America, Europe and China, the outlook remains uncertain. The wide-body jets used for long-haul flights stand idle. Carriers that rely on business passengers and hub airports are struggling. Although some American airlines expect a return to near-full operation next year, a second wave of covid-19 could dash these hopes. A small outbreak in Beijing in June set back the recovery in Chinese domestic flights. As one senior aerospace executive says, “It’s hardest to talk about the next 12 months.”
According to Cirium, another consultancy, around 35% of the global fleet of around 25,000 aircraft is still parked—less than the two-thirds at the height of the crisis in April but still terrible. Even if traffic recovers to 80% of last year’s levels in 2021, as some optimists expect, plenty of aeroplanes will remain on the ground. Citigroup, a bank, forecasts excess capacity of 4,000 aircraft in 18 months’ time.
Aircraft-makers, which had been preparing to crank up production, are forced to do the opposite. Airbus, with a backlog of more than 6,100 orders for its A320 jets, was rumoured to be raising output from 60 of the popular narrow-bodies a month to 70. Instead it is making 40. Its long-haul planes have suffered similar declines. Boeing’s situation is made worse by the protracted grounding in 2019 of its 737 MAX, a rival to the A320, in the wake of two fatal crashes. It has kept making the aircraft and hopes to have it recertified for flight later this year. The American firm will slowly increase production to 31 a month by the start of 2022. But like Airbus, it too has announced cuts to wide-body production.
This will open a big gap between what the pair, along with Embraer and Bombardier, makers of smaller regional jets, hoped to sell and what they actually will (see chart 2). According to consultants at Oliver Wyman, by 2030 the global fleet will be 12% smaller than if growth had continued unabated. That amounts to 4,700 fewer planes, which could translate to $300bn or so in forgone revenue for Boeing and Airbus, according to a rough calculation by The Economist.
With so many aircraft sitting idle and balance-sheets in tatters, airlines are getting rid of planes. Even low fuel prices will not save older, thirstier models. Four-engine wide-bodies are all but finished. On July 17th British Airways (BA) said it would retire all 31 of its Boeing 747 jumbo jets. IBA, an aviation-research firm, expects 800 planes around the world to be retired early.
Not all orders will dry up. Airlines, as well as leasing firms, which now own close to half the global fleet, are contractually obliged to take aircraft on order. Many buyers will have made pre-delivery payments of up to 40% of the price. Airbus and Boeing are, to varying degrees, pushing customers to take deliveries. Most negotiations have centred on deferring deliveries. EasyJet, a British low-cost carrier, has pushed back delivery of 24 Airbuses by five years. At Boeing, delays related to the problems of the 737 MAX allow airlines to ask for refunds. More assertively, Airbus’s boss, Guillaume Faury, does not rule out suing customers who renege on their orders.
A stock of “white tails”, as unsold planes are known in industry vernacular, may be the price to pay for protecting a supply chain that had been investing heavily for ever-higher production rates. Airbus will make 630 planes this year but deliver only 500, Citigroup reckons. It has the balance-sheet to carry inventory, thinks Sandy Morris of Jefferies, another bank. The new rate will preserve jobs and industrial efficiency, and make an eventual ramp-up easier.
Even this artificially high production will struggle to sustain the planemakers’ supply chain, however. This comprises manufacturers of engines (like Rolls-Royce and GE), producers of fuselages and other parts (such as Spirit AeroSystems), specialised materials firms (Hexcel and Woodward) and companies that produce avionics and electrical systems (including Honeywell and Safran). And that is not counting their myriad smaller suppliers; Boeing’s MAX supply chain stretches to around 600 firms. Many had invested heavily before the crisis, expecting strong demand. Defence contracts, which firms from Airbus and Boeing down are involved in and which covid-19 has not really affected, provide only partial respite. On July 29th Boeing said it had delivered just 20 planes in the second quarter, down from 90 a year ago, and that commercial-aircraft revenues had dropped by 65%, to $1.6bn. The next day Airbus and Safran also disclosed sharp falls in revenue.
The engine-makers provide a case in point. Besides lower demand for their kit—Rolls-Royce was gearing up to supply 500 units a year to Airbus but will now probably make 250—they face a collapsing aftermarket for spares and fewer overhauls, points out David Stewart of Oliver Wyman. Airlines with in-house maintenance divisions can scavenge parts or whole engines from grounded planes. Rolls-Royce, whose engines power two-fifths of all long-haul jets, has suspended dividends, said it would cut 9,000 jobs and taken a £2bn ($2.6bn) loan. It may have to ask investors for another £2bn. GE’s second-quarter revenues from its aviation business fell by 44%, year on year, dragging down the conglomerate’s overall results (see article).
At the other end of the air-travel industry are airports. About 60% of their revenues comes from charges on airlines and passengers, and the rest from things like retail and parking. All are taking a hit. Airport shops and restaurants in America will lose $3.4bn between now and the end of 2021, forecasts the Airport Restaurant & Retail Association. As Mr de Oliveira of ACI World notes, two in three airports were losing money before the crisis; now all are. Some smaller ones may close if subsidies to support tourism from regional and national governments start to dwindle. Outside America commercial operators have not been treated by governments as generously as airlines have.
In July Standard & Poor’s again downgraded the debt of four European airports, including Amsterdam’s Schiphol and Zurich, and placed London Gatwick and Rome on watch, questioning their ability to raise charges while airlines continue to bleed cash. The rating agency estimates a cut of €10bn ($11.8bn) in planned capital spending by European airports in 2020-23, which may crimp efforts to install contactless technology that could help reassure travellers that terminals are safe to re-enter.
As dark as the skies have grown for the air-travel complex, there are some opportunities. Airlines are restructuring. Europe’s big legacy carriers, under pressure from low-cost rivals, are slashing costs. BA has suspended 30,000 workers and wants to rehire them on less generous terms. Bankruptcies and cutbacks will leave gaps in the market, aircraft are cheap, once-scarce pilots are plentiful, and airports will have spare slots, if they are allowed to redistribute them.
Strong challenger carriers have a chance to gain market share. Wizz Air, a Hungarian low-cost carrier, hopes to add capacity by March; its main markets in central and eastern Europe have been hurt less by the pandemic than those elsewhere, its customers are generally young and less worried about getting on a plane, and two-thirds of demand is related to visiting family and friends, which seems more resilient to covid-19 than business travel is.
Some carriers may radically rethink their financial structures, which could help leasing grow even faster. Domhnal Slattery, boss of Avolon, a big lessor, thinks that heavy debts airlines incur to survive the pandemic may convince many of them that they need not own aircraft but should instead concentrate on sales and marketing, just as hotel chains have turned their backs on owning property.
The industry is also rethinking its environmental footprint. Bolder airlines with stronger balance-sheets may use the crisis to renew their fleets, making them greener. They have bargaining power: everything is negotiable, including deferrals, prepayments and price.
Rolling with the punches
Warren East, boss of Rolls-Royce, suspects that the “pre-covid call for sustainability will come back stronger than ever”. Airbus is still committed to the journey to zero-emissions flying, Mr Faury says; he sees it as an opportunity. Boeing would have to respond to stay competitive. European governments in particular regard it as a priority. France’s €15bn aid package for its aerospace sector includes a €1.5bn research-and-development fund to help Airbus launch a zero-emissions short-haul passenger jet by 2035 (probably powered by either biofuels or hydrogen). Mr Faury accepts that there is less money to invest. But also, he says, “more need”. The crisis has led to greater collaboration with suppliers that could make innovation “faster, leaner and cheaper” (though that has meant laying off 15,000 workers).
China, desperate to become a power in commercial aerospace, may see the disruption as a way to speed up entry into the global market, says Robert Spingarn of Credit Suisse, a bank. He speculates that Brazil’s Embraer, whose merger with Boeing fell apart in April, might collaborate with China’s COMAC to build a plane capable of competing against Airbus and Boeing. The Brazilians could supply the industrial knowhow and the Chinese the industrial might.
To the masked passengers on half-empty planes, boarded from ghost-town airports of shuttered shops, it may seem that the experience of flying will never be the same again. Yet aviation has bounced back before. It is likely to do so again—and may change for the better in the process. ■
Editor’s note: Some of our covid-19 coverage is free for readers of The Economist Today, our daily newsletter. For more stories and our pandemic tracker, see our hub
This article appeared in the Business section of the print edition under the headline “Terminal conditions”
Please enable cookies on your web browser in order to continue.
The new European data protection law requires us to inform you of the following before you use our website:
We use cookies and other technologies to customize your experience, perform analytics and deliver personalized advertising on our sites, apps and newsletters and across the Internet based on your interests. By clicking “I agree” below, you consent to the use by us and our third-party partners of cookies and data gathered from your use of our platforms. See our Privacy Policy and Third Party Partners to learn more about the use of data and your rights. You also agree to our Terms of Service.
FOX Business’ Jackie DeAngelis breaks down the market’s reaction to the coronavirus.
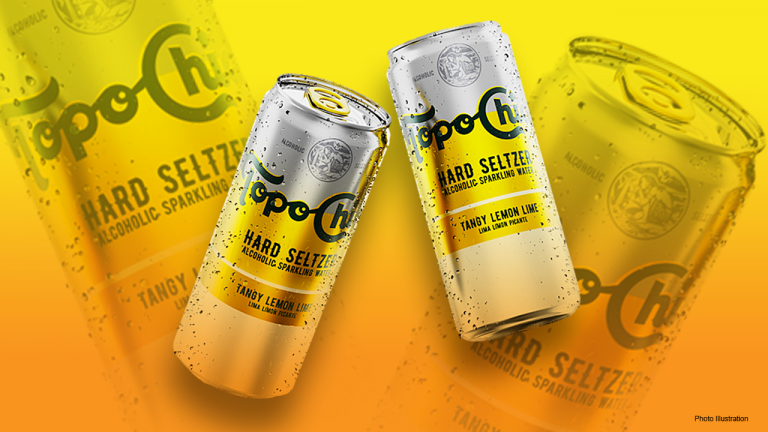
The Coca-Cola Company will be expanding its brand portfolio to include a hard seltzer beverage later this year, a spokesperson at the company has confirmed for FOX Business.
The new drink’s name is Topo Chico Hard Seltzer and it will be made from Topo Chico Mineral Water – a sparkling water company that has sourced and bottled water in Monterrey, Mexico since 1895 and was bought by Coca-Cola in 2017 for $220 million.
Topo Chico has reportedly “been popular with many mixologists,” according to a press release issued by Coca-Cola on Thursday.
Moreover, Coca-Cola’s boozy beverage will be offered in select Latin American cities at some point in 2020. An exact date has not been specified. Though, the U.S. is scheduled to distribute Topo Chico Hard Seltzer in 2021, a Coca-Cola spokesperson told FOX Business.
The Coca-Cola Company – which had an estimated 43.3 percent of the U.S. market share in 2018, according to research from Statista – is no stranger to sparkling drinks or alcoholic beverages. In fact, the company has been building on these drink categories in recent years domestically and abroad.
Outside of Topo Chico, Coca-Cola’s water brands Dasani, Smartwater, I LOHAS and Ciel all hve sparkling variants, and in late 2019, the company launched its flavored sparkling water brand AHA.
Meanwhile, in Japan, Coca-Cola introduced Lemon-Do in May 2018. The lemon-flavored alcoholic beverage rolled out with ABV contents of three-, five-, seven- and nine-percent in a nine-month span, according to a report from The Wall Street Journal last year.
Interestingly enough, Coca-Cola President and CEO James Quincy told Yahoo! Finance that the company would not be selling alcoholic beverages in the U.S. after the successful launch of Lemon-Do.
However, sparkling soft drinks declined by 12 percent in North America, Western Europe and India, according to Coca-Cola’s Second Quarter 2020 Results. The cause was “due to pressure in away-from-home channels,” the report stated.
The hard seltzer market, on the other hand, has seen explosive growth in the last two years. The category surpassed $1 billion in off-premise sales during the week of the Fourth of July holiday, a to market research report from Nielsen showed earlier this month.
Beer and alcohol companies have launched or have announced plans to launch hard seltzer brands unlike most soft drink companies.
Monster Beverage Corp is one soft drink company that has reportedly discussed hard seltzer’s potential internally, according to a report from The Motley Fool, but Coca-Cola also has a minority stake in the company 16.7 percent, which it bought in June 2015 for $2.15 billion.
That means that, for each share of Apple stock that an investor owns, they’ll receive three additional shares. It also makes single shares in Apple more affordable for investors to buy. It follows a similar move Apple made in 2014, when it offered a 7-to-1 stock split. At the time, Apple was trading above $600 per share. The split brought shares of Apple to about $92 a share.
Stock splits are cosmetic and do not fundamentally change anything about the company, other than possibly making the shares accessible to a larger number of investors because of their cheaper price.
Since Apple stock currently trades above $380, it means investors should expect to again have a chance to buy a share of Apple for around $100, depending on where the stock trades at the end of August.
The shares will be distributed to shareholders at the close of business on August 24, and trading will begin on a split-adjusted basis on August 31.
This is Apple’s fifth stock split since it went public. It also split on a 7-for-1 basis on June 9, 2014; a 2-for-1 basis on February 28, 2005; a 2-for-1 basis on June 21, 2000; and on a 2-for-1 basis on June 16, 1987.
TechCrunch fait partie de Verizon Media. Cliquez sur J’accepte afin d’autoriser Verizon Media et ses partenaires à utiliser des cookies et des technologies similaires pour accéder à votre appareil, utiliser vos données (y compris votre position géographique), comprendre vos centres d’intérêt, diffuser des publicités personnalisées et mesurer leur efficacité. Nous vous présenterons également des publicités personnalisées sur les produits de ses partenaires.
Découvrez-en plus sur la façon dont nous utilisons vos données dans notre Vie Privée. Après avoir confirmé ici vos choix en matière de vie privée, vous pouvez les modifier à tout moment en consultant votre Tableau de bord sur la vie privée.
Cliquez sur En savoir plus pour comprendre comment Verizon Media et nos partenaires collectent et utilisent les données, et pour personnaliser les paramètres.
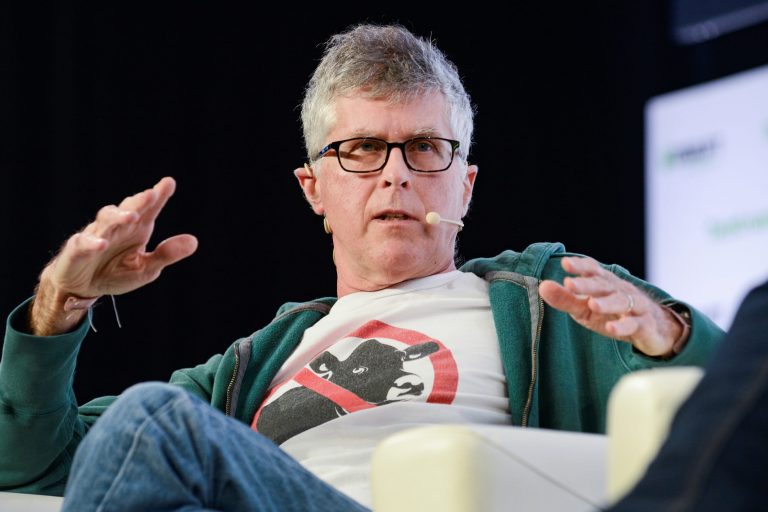
Impossible Foods CEO Patrick Brown said the launch of the Impossible Burger in Walmart is a “very significant step” for the company, as the discount retailer is the biggest seller of meat in the U.S.
“Walmart is the largest food retailer in the world,” Brown said Thursday on “Closing Bell.” “It has a huge presence — 90% of the U.S. population lives within a mile of a Walmart store.”
Brown said the partnership is exactly the kind the company wants, especially considering Walmart’s commitment to sustainability. The launch brings Impossible to more than 2,000 stores in all 50 states, as well as on the Walmart website and app.
The partnership boosts the vegan burger’s availability to more than 8,000 retail locations nationwide, as the company’s retail footprint has become 50 times larger than it was six months ago. Impossible’s rival Beyond Meat is already available in retailers such as Kroger.
Brown said he does not view the two companies in competition with each other and he wishes Beyond luck in their business. Instead, he said both companies are competing against the meat industry. He described Impossible Foods’ mission as completely replacing the need for animals in the food system.
More than 90% of Impossible customers are current meat consumers, Brown said, meaning purchases largely come from customers selecting its product as an alternative to meat. With this in mind, Brown said he was happy the product will be sold in the meat aisle of stores so it can be where buyers are looking.
“I think we’re going to see, with the disruption of the meat industry, more first-time buyers that are looking elsewhere for their meat,” he said. “It’s very sticky. A majority of them become repeat customers.”
We use cookies to ensure that we give you the best experience on our website. If you continue to use this site we will assume that you are happy with it.