FAA approves Rocket Lab to resume launches after company identified cause of July 4 failure – CNBC

Rocket Lab’s Electron rocket lifts off on July 4, 2020.

Rocket Lab

Small rocket builder Rocket Lab is going back to the launchpad in August, as the company said it diagnosed the cause of its recent launch failure and received approval from the Federal Aviation Administration to resumes launches.

“We were able to quickly reconstruct what happened, and the [investigation] board was able to confidently narrow down the issue to a single eligible connection,” Rocket Lab CEO Peter Beck told reporters during a briefing on Friday.

The company’s Electron rocket launched its 13th mission on July 4, carrying seven small satellites bound for orbit. But the rocket never reached its destination, despite the early stages of the launch going according to plan, as a disconnection in its electrical system caused the rocket’s engine to shut down. Rocket Lab says the root of the issue was an electrical system that wasn’t secured, which led to the part overheating and then melting during flight.

Alongside FAA investigators, the company reviewed over 25,000 channels of data from the launch to identify the cause of the accident.

“This disconnection was incredibly unusual because it was able to evade all of the pre-flight acceptance testing,” Beck said. “It’s a very sneaky and tricky issue to try and screen for.”

Rocket Lab has built more than 720 of these electrical components, Beck noted. The company made a “slight change” to its production process and will be screening for the issue in the rockets its built.

“Anybody who flies on Electron now is going to be flying on a more reliable vehicle than they did before,” Beck said.

First U.S. launch coming up

Rocket Lab is the industry leader in building and launching small rockets, targeting the growing market of satellites and spacecraft that are anywhere between the size of a toaster to a refrigerator. Its Electron rocket is priced at about $7 million per launch and is 55 feet tall, or about a fifth the size of a SpaceX Falcon 9 rocket. 

Started in 2006, the company has about 600 employees and is backed by a host a VC firms and, in recent years, has grown its valuation to more than $1.2 billion. It’s based in Long Beach, California but was founded by Beck in New Zealand, where it has a privately-built launchpad.

Beck said that “there was a financial loss” from the July 4 failure “because we’re not launching.” But he downplayed the significance of that loss, saying that it “wasn’t really a big deal” and noting that the company still has cash set aside from its $140 million round of funding in November 2019.

Rocket Lab has launched its Electron rocket to space 12 times. It first reached orbit in January 2018 and is closing in on beginning launches from a second pad in Virginia. The first launch from that U.S. location, called LC-2, will be “a few weeks” after the August launch, Beck said.

“We haven’t launched this month and we’re trying to be on a one month cadence so we’re at least four weeks behind,” Beck added.

To date, the company has successfully deployed 53 payloads.

Additionally, the company last year expanded into the spacecraft building business itself with its Photon satellite platform. It’s grown its business to include building satellite hardware and earlier this year passed key milestones in developing a system to reuse its rockets — by snagging them out of the sky using parachutes and a helicopter.

Subscribe to CNBC PRO for exclusive insights and analysis, and live business day programming from around the world.

Market Wrap: Bitcoin Pushes to $11450, DeFi Value Locked Now at $4B – CoinDesk – CoinDesk

Bitcoin and ether continue to make gains Friday and stakeholders are increasingly investing their crypto into DeFi.

  • Bitcoin (BTC) trading around $11,333 as of 20:00 UTC (4 p.m. ET). Gaining 2% over the previous 24 hours.
  • Bitcoin’s 24-hour range: $10,974-$11,460
  • BTC above 10-day and 50-day moving averages, a bullish signal for market technicians.

btcjul31
Bitcoin trading on Coinbase since July 28.
Source: TradingView

Bitcoin’s price pushed as high as $11,460 on increased buying volume Friday, continuing its bullish run to cap a week of economic uncertainty. 

Read More: Bitcoin on Track for Highest July Price Gain in 8 Years

“The U.S. Q2 GDP results were rough and traditional markets are seeing a bit of risk off – a sharp move lower in yields and weakness in stocks,” Dan Koehler, liquidity manager for cryptocurrency exchange OKCoin, told CoinDesk. “It’s a crucial time for bitcoin, in my view.”

Indeed, stocks are taking a beating Friday, with major global indexes down or flat.

btcvsstovcks
Bitcoin (gold), S&P 500 (blue), FTSE 100 (green) and Nikkei 225 (red) in July.
Source: TradingView

Bitcoin beat major equity indexes for July, up over 20% for the month. “It will be interesting to see how bitcoin behaves in a risk-off environment this time around, having broken and thus far held above $10,400,” added OKCoin’s Koehler.

Read More: Banks in US Can Now Offer Crypto Custody Services, Regulator Says

Michael Rabkin, head of institutional sales at crypto trading firm DV Chain, said a positive news cycle on the crypto front is helping the market. “We’ve been seeing more buying over the last few days, specifically since the past week’s announcement which would allow banks to hold custody,” he said. 

“There’s definitely a more bullish sentiment since that announcement came out and as we’ve seen, has resulted in upward momentum,” Rabkin added

Mostafa Al-Mashita of Global Digital Assets, a digital assets-focused merchant bank, said alternative cryptocurrencies, or altcoins, is where he expects traders to take profits near-term. “The market is consolidating as altcoins catch up to the recent bitcoin pump,” he said. “I would expect altcoins to lead for a few days before bitcoin rising again.”

Read More: Coinbase Considering 19 Additional Cryptos for Exchange Listing

DeFi locked at $4B

Ether (ETH), the second-largest cryptocurrency by market capitalization, was up Friday, trading around $344 and climbing 3.1% in 24 hours as of 20:00 UTC (4:00 p.m. ET). 

Since June 1, the total value locked in Ethereum-powered decentralized finance, or DeFi, has risen 300% from $1 billion to $4 billion, according to data aggregator DeFi Pulse.

tvljul31
Total locked in DeFi the past three months.
Source: DeFi Pulse

In just two months, total bitcoin locked in DeFi more than quadrupled from 4,975 to 20,610 BTC. Total ether locked in DeFi has grown 60%, from 2.6 million to 4.2 million ETH. Stablecoin dai locked is up 19%, from 365 million to 435 million. 

Read More: Aave’s LEND Token Jumps 23% on Plan for Liquidity Mining

Azamat Malaev, co-founder of HodlTree, a new DeFi protocol for interest-yielding tokens, said the catalyst for this growth was investors locking crypto with a particular big DeFi lender to achieve “yield” or profit. ”It started with the launch of the Compound token distribution on June 15,” he said. “And, of course, with a time delay information began to spread.” 

Other markets

Digital assets on the CoinDesk 20 are mostly higher Friday. Notable winners as of 20:00 UTC (4:00 p.m. ET): 

Notable losers as of 20:00 UTC (4:00 p.m. ET):

Read More: Chainlink’s Soaring Token Shows Lucrative ‘Oracle’ Role 

  • Gold is up 0.90% and at $1,973 as of press time.
  • Oil is flat, in the green 0.12%. Price per barrel of West Texas Intermediate crude: $40.37

Read More: Dollar Falls to Lowest Level in 2 Years While Gold, Silver, Bitcoin Shine

  • U.S. Treasury bonds all slipped Friday. Yields, which move in the opposite direction as price, were dow most on the two-year, in the red 12%.

Read More: Ripple Paid MoneyGram $15.1M in ‘Market Development Fees’ in Q2

coindesk20_endofarticle_banner_1500x600
Disclosure

The leader in blockchain news, CoinDesk is a media outlet that strives for the highest journalistic standards and abides by a strict set of editorial policies. CoinDesk is an independent operating subsidiary of Digital Currency Group, which invests in cryptocurrencies and blockchain startups.

Apple Inc. stock rises Friday, outperforms market – MarketWatch

Shares of Apple Inc.
AAPL,
+10.46%

jumped 10.47% to $425.04 Friday, on what proved to be an all-around positive trading session for the stock market, with the NASDAQ Composite Index
COMP,
+1.48%

rising 1.49% to 10,745.27 and the Dow Jones Industrial Average
DJIA,
+0.43%

rising 0.44% to 26,428.32. This was the stock’s third consecutive day of gains. Apple Inc. hit a new 52-week high, surpassing its previous peak of $399.82, which the company reached on July 13th.

The stock outperformed some of its competitors Friday, as Microsoft Corp.
MSFT,
+0.54%

rose 0.54% to $205.01, Alphabet Inc. Cl A
GOOGL,
-3.27%

fell 3.28% to $1,487.95, and International Business Machines Corp.
IBM,
+0.03%

rose 0.03% to $122.94. Trading volume (92.1 M) eclipsed its 50-day average volume of 33.0 M.

Click here to let us know what you think about this content.


Editor’s Note: This story was auto-generated by Automated Insights using data from Dow Jones and FactSet. See our market data terms of use.

Universal cuts workforce as theme parks face major hurdles from pandemic – Orlando Sentinel

Unfortunately, our website is currently unavailable in most European countries. We are engaged on the issue and committed to looking at options that support our full range of digital offerings to the EU market. We continue to identify technical compliance solutions that will provide all readers with our award-winning journalism.

Despite Historic Plunge, Europe’s Economy Flashes Signs of Recovery – The New York Times

LONDON — Before the pandemic, a traditional state of play prevailed in the enormous economies on the opposite sides of the Atlantic. Europe — full of older people, and rife with bickering over policy — appeared stagnant. The United States, ruled by innovation and risk-taking, seemed set to grow faster.

But that alignment has been reordered by contrasting approaches to a terrifying global crisis. Europe has generally gotten a handle on the spread of the coronavirus, enabling many economies to reopen while protecting workers whose livelihoods have been menaced. The United States has become a symbol of fecklessness and discord in the face of a grave emergency, yielding deepening worries about the fate of jobs and sustenance.

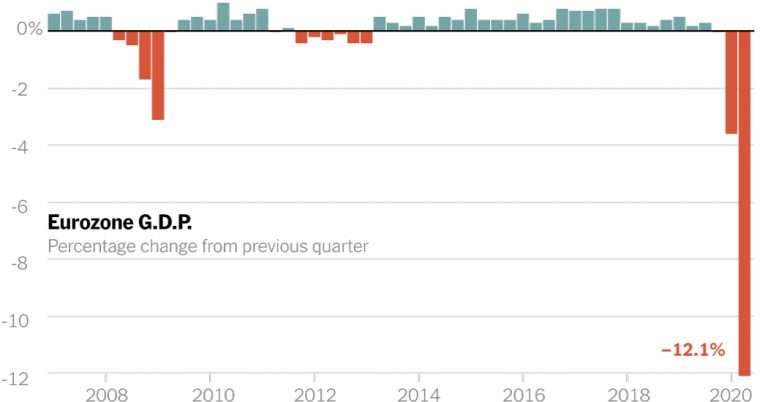
On Friday, Europe released economic numbers that on their face were terrible. The 19 nations that share the euro currency contracted by 12.1 percent from April to June from the previous quarter — the sharpest decline since 1995, when the data was first collected. Spain fell by a staggering 18.5 percent, and France, one of the eurozone’s largest economies, declined 13.8 percent. Italy shrunk by 12.4 percent.

Europe appeared even worse than the United States, which the day before recorded the single-worst three-month stretch in its history, tumbling by 9.5 percent in the second quarter.

But beneath the headline figures, Europe flashed promising signs of strength.

Germany saw a drop in the numbers of unemployed, surveys found evidence of growing confidence amid an expansion in factory production, while the euro continued to strengthen against the dollar as investment flowed into European markets — signs of improving sentiment.

These contrasting fortunes underscored a central truth of a pandemic that has killed more than 670,000 people worldwide: The most significant cause of the economic pain is the virus itself. Governments that have more adeptly controlled its spread have commanded greater confidence from their citizens and investors, putting their economies in better position to recuperate from the worst global downturn since the Great Depression.

“There is no economic recovery without a controlled health situation,” said Ángel Talavera, lead eurozone economist at Oxford Economics in London. “It’s not a choice between the two.”

European confidence has been bolstered by a groundbreaking agreement struck in July within the European Union to sell 750 million euro ($892 million) worth of bonds that are backed collectively by its members. Those funds will be deployed to the hardest hit countries like Italy and Spain.

The deal transcended years of opposition from parsimonious northern European countries like Germany and the Netherlands against issuing common debt. They have balked at putting their taxpayers on the line to bail out southern neighbors like Greece while indulging in crude stereotypes of Mediterranean profligacy. The animosity perpetuated the sense that Europe was a union in name only — a critique that has been muted.

The United States has spent more than Europe on programs to limit the economic damage of the pandemic. But much of the spending has benefited investors, spurring a substantial recovery in the stock market. Emergency unemployment benefits have proved crucial, enabling tens of millions of jobless Americans to pay rent and buy groceries. But they were set to expire on Friday and there were few signs that Congress would extend them.

Europe’s experience has underscored the virtues of its more generous social welfare programs, including national health care systems.

Americans feel compelled to go to work, even at dangerous places like meatpacking plants, and even when they are ill, because many lack paid sick leave. Yet they also feel pressure to avoid shops, restaurants and other crowded places of business because millions lack health insurance, making hospitalization a financial catastrophe.

“Europe has really benefited from having this system that is more heavily dominated by welfare systems than the U.S.,” said Kjersti Haugland, chief economist at DNB Markets, an investment bank in Oslo. “It keeps people less fearful.”

The more promising situation in Europe is neither certain nor comprehensive. Spain remains a grave concern, with the virus spreading, threatening lives and livelihoods. Italy has emerged from the grim calculus of mass death to the chronic condition of persistent economic troubles. Britain’s tragic mishandling of the pandemic has shaken faith in the government.

If short-term factors look more beneficial to European economies, longer-term forces may favor the United States, with its younger population and greater productivity.

A sense of European-American rivalry has been provoked by the bombast of a nationalist American president, making the pandemic a morbid opportunity to keep score.

“There is a certain amount of triumphalism,” said Peter Dixon, a global financial economist at Commerzbank in London. “People are saying, ‘Our economy has survived, we are doing OK.’ There’s a certain amount of European schadenfreude, if I can use that word, given everything that Trump has said about the U.S.”

But for now, Europe’s moment of confidence is palpable, most prominently in Germany, the continent’s largest economy.

Though the German economy shrank by 10.1 percent from March to June — its worst drop in at least half a century — the number of officially jobless people fell in July, in part because of government programs that have subsidized furloughed workers.

Surveys show that German managers — not a group inclined toward sunny optimism — have seen expectations for future sales return to nearly pre-virus levels. That buoyancy translates directly into growth, emboldening companies to rehire furloughed workers.

Ziehl-Abegg, a maker of ventilation systems for hospitals, factories and large buildings, recently broke ground on a 16 million euro ($19 million) expansion at a factory in southern Germany.

“If we wait to invest until the market recovers, that’s too late,” said Peter Fenkl, the company’s chief executive. “There are billions of dollars in the market ready to be invested and just waiting for the signal to kick off.”

The euro has gained more than 5 percent against the dollar so far this year, according to FactSet. European markets have been lifted by international money flowing into so-called exchange-traded funds that purchase European stocks. The Stoxx 600, an index made up of companies in 17 European countries, appears set for a second straight month of gains outpacing the S&P 500.

The French oil giant Total saw demand for its products in Europe drop by nearly one third in the second quarter of the year, but a powerful recovery has been gaining momentum, said the company’s chairman and chief executive, Patrick Pouyanné.

“Since June, we have seen a rebound here in Europe,” he said during a call with analysts. “Activity in our marketing networks is back to, I would say, 90 percent of the pre-Covid levels.”

France, Europe’s second largest economy, has been buttressed by aggressive government spending. President Emmanuel Macron has mobilized more than 400 billion euros ($476 billion) in emergency aid and loan guarantees since the start of the crisis, and is preparing an autumn package worth another 100 billion euros.

Those funds paid businesses not to lay off workers, allowing more than 14 million employees to go on paid furlough, stay in their homes, accumulate modest savings and continue spending. Delayed deadlines for business taxes and loan payments spared companies from collapse.

In the second quarter, when France was still partially locked down, the country’s economy contracted by nearly 14 percent. Tourism, retail and manufacturing, the main pillars of the economy, ground to a halt.

But services, industrial activity and consumer spending have all shown signs of improvement. The Banque de France, which originally expected the economy to shrink more than 10 percent this year, recently forecast less damage.

In Spain, a sense of recovery remains distant. Its economy shrunk by nearly 19 percent from April to June. The nation’s unemployment rate exceeds 15 percent, and could surge higher if a wage subsidy program for furloughed workers is allowed to expire in September.

Spain officially ended its coronavirus state of emergency on June 21, but has since suffered an increase in infections. The economic impacts have been compounded by Britain’s decision to force travelers returning from Spain to quarantine for two weeks. Tourism accounts for 12 percent of Spain’s economy.

Italy is also highly exposed to tourism. Its industry is concentrated in the north of the country, which saw the worst of coronavirus. The central bank expects the Italian economy to contract by nearly 10 percent this year.

But exports surged more than one-third in May compared with the previous month. That left them below pre-pandemic levels, yet on par with German and American competitors, according to Confindustria, an Italian trade association.

“We are starting to slowly recover after the most violent downfall in the last 70 years,” said Francesco Daveri, an economist at Bocconi University in Milan.

Europe’s fortunes appear on the mend because its people are more likely to trust their governments.

Denmark acted early, imposing a strict lockdown while paying wage subsidies that limited unemployment. Denmark suffered far fewer deaths per capita than the United States and Britain.

With the virus largely controlled, Denmark lifted restrictions earlier, while Danes heeded the call to resume commercial life. The Danish economy is expected to contract by 5.25 percent this year, according to the European Commission, with a substantial improvement in the second half of the year.

In the United States, people have wearied of bewildering and conflicting advice from on high against a backdrop of more than 150,000 deaths.

The result has been record surges of new cases along with a syndrome likely to persist — an aversion to being near other people. That spells leaner prospects for retail, hotels, restaurants and other job-rich areas of the American economy.

Liz Alderman reported from Paris. Emma Bubola contributed reporting from Milan, Raphael Minder from Madrid and Stanley Reed and Eshe Nelson from London.

James Murdoch Resigns From News Corp. Board, Citing “Disagreements” Over Editorial Content – Hollywood Reporter

The mogul sent a letter of resignation on Friday afternoon.

Former 21st Century Fox CEO James Murdoch has resigned from the board of News Corp., the parent company of the Wall Street Journal.

In a letter of resignation filed Friday afternoon, Murdoch wrote: “My resignation is due to disagreements over certain editorial content published by the Company’s news outlets and certain other strategic decisions.”

James Murdoch had been on News Corp.’s board of directors since 2013.

News Corp. is one of two media companies controlled by James’ father Rupert Murdoch and the Murdoch family. The other is Fox Corp., the parent company of Fox News and the Fox broadcast network, which was created after 21st Century Fox sold its entertainment assets to The Walt Disney Company.

Murdoch stepped down as Fox CEO following the sale, with his brother Lachlan Murdoch becoming CEO, and father Rupert becoming co-chairman. News Corp., which owns the Wall Street Journal, Dow Jones, New York Post, News U.K. and newspaper and TV assets in Australia, is run by CEO Robert Thomson.

After leaving the Fox fold, Murdoch started his own company, Lupa Systems, which has invested in technology companies and other firms. Lupa Systems has acquired stakes in Vice Media, tech startup Betalab, and is pursuing a stake in MCH Group, the parent company of the Art Basel fair. Lupa Systems and Joe Marchese’s Attention Capital also acquired a majority stake in Tribeca Enterprises last year, the parent organization of the Tribeca Film Festival. 

Elon Musk says China rocks while the U.S. is full of complacency and entitlement – CNBC

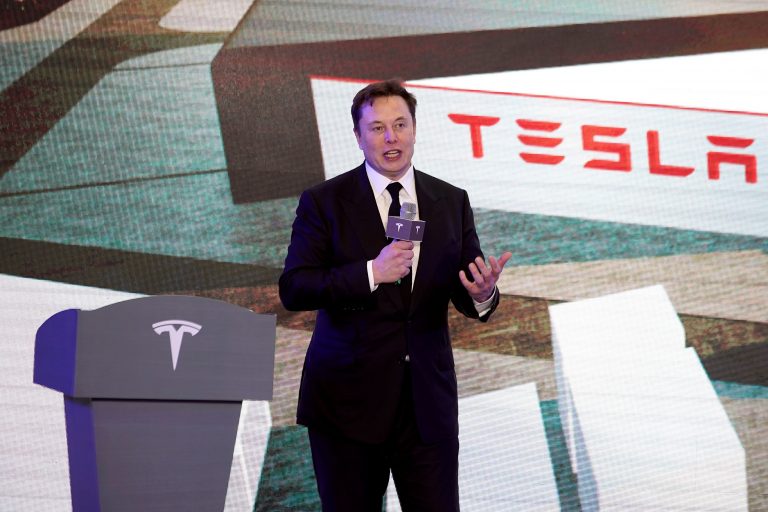
Tesla Inc CEO Elon Musk speaks at an opening ceremony for Tesla China-made Model Y program in Shanghai, China January 7, 2020.

Aly Song | Reuters

Tesla and SpaceX CEO Elon Musk lamented the “entitled” and “complacent” character of people in the United States, and lauded the “smart” and “hard working people” of China, in the first installment of a three-part interview with Automotive News’ “Daily Drive” podcast published Friday. 

Specifically, Musk criticized New York and California — states that have supported his businesses, especially Tesla, with considerable tax breaks, regulatory credits and other government help.

Automotive News publisher Jason Stein, who conducted the interview, asked Musk, “How about China as an EV strategy leader in the world?”

Musk replied: “China rocks in my opinion. The energy in China is great. People there – there’s like a lot of smart, hard working people. And they’re really — they’re not entitled, they’re not complacent, whereas I see in the United States increasingly much more complacency and entitlement especially in places like the Bay Area, and L.A. and New York.”

Last year, Chinese government officials helped Tesla secure loans worth around $1.6 billion to construct and begin manufacturing vehicles at the company’s relatively new Shanghai factory. This year, the Shanghai government helped Tesla get back to normal operations quickly, at its new plant, after the region was struck by a Covid-19 outbreak and issued widespread quarantines that temporarily suspended manufacturing there.

Musk pointed out, Telsa has not received as much assistance from the government in China as domestic companies there. “They have been supportive. But it would be weird if they were more supportive to a non-Chinese company. They’re not,” he said.

The enthusiasm the mercurial Musk expressed for China contrasted with his expressed disdain for communism. In a tweet on Monday this week, Musk mocked social welfare programs in general, and Karl Marx’s “Das Kapital.”

During the Automotive News podcast, Musk also compared the U.S., California and New York to sports teams about to lose their winning status.

He said:

“When you’ve been winning for too long you sort of take things for granted. The United States, and especially like California and New York, you’ve been winning for too long. When you’ve been winning too long you take things for granted. So, just like some pro sports team they win a championship you know a bunch of times in a row, they get complacent and they start losing.”

Tesla and the states

Among U.S. automakers, “Tesla has had the least government support of any car company,” Musk said.

He boasted about Tesla’s repayment of a loan to the U.S. Department of Energy ahead of schedule.

In June 2009, the Obama-era Department of Energy awarded Tesla a $465 million loan to set up a vehicle assembly plant in Fremont, California, and to begin production of its flagship all-electric sedan, the Model S. Tesla repaid it with interest by May 2013, nine years ahead of schedule. 

The DOE loan was small compared with the tens of billions in TARP loans that went to bail out General Motors and Chrysler during the financial crisis that began in 2008.

However, Tesla has benefited from other forms of government assistance in the U.S. According to analysis by the Los Angeles Times, Tesla’s government assistance in the U.S. has surpassed $4.9 billion.

Tesla’s government support in California has included more than $220 million in sales and use tax exclusions from the California Alternative Energy and Advanced Transportation Financing Authority, as well as zero emission vehicle and solar renewable energy credits granted by the state. The sale of these regulatory credits were a major factor in Tesla’s profitability in the past four quarters. 

As CNBC and others previously reported, New York state spent $959 million on a solar-panel factory in Buffalo, now operated by Tesla, in a drive to bring more than 1,000 high-paying tech and manufacturing jobs to the state.

Tesla hasn’t fulfilled its employment obligations in New York so far. A financial filing out this week revealed that Tesla has obtained a full-year extension from the state in order to meet the head count requirement. If it does not, Musk’s electric car and renewable energy venture will have to pay back $41 million to the Empire State.

Tesla stock and sales

On the podcast, Musk also celebrated the fact that Tesla is now seen as a “legitimate” American and multinational automaker. While it used to be an upstart and underdog, Automotive News asked him what was going on with the soaring price of Tesla shares, which are up more than 240% this year, and whether Musk felt a need to manage investors’ expectations.

The CEO demurred:

“It’s not worth trying to massage the stock market or manage investor expectations. It’s just. You know? At the end of the day, if you make great cars and the company’s healthy and making great products investors will be happy…If you make lousy products your customers will be unhappy and then your investors will be unhappy.”

Elon Musk, chairman and chief executive officer of Tesla Motors, speaks in front of a Tesla Model S electric car on day two of the 2010 North American International Auto Show in Detroit, Michigan.

Daniel Acker | Bloomberg | Getty Images

He also gave this advice to other entrepreneurs: 

“My advice, you know, to corporate America or companies worldwide is spend less time on marketing presentations and more time on your product. Honestly that should be the number one thing taught in business schools. Put down that spreadsheet and that PowerPoint presentation and go and make your product better.”

He also predicted that online car sales, and delivering cars direct to consumers, rather than vehicle sales through stores or traditional dealerships, would become even more of a standard, after Covid-19. 

Tesla saw “strong orders through the whole pandemic,” Musk said. Tesla deliveries that declined about 5% for the second quarter of 2020. Due to Covid-19 impacts, most other automakers saw sales plunge more than 30% during the same period. The CEO concluded, “Having a traditional dealer situations I think seems increasingly unnecessary and I think probably the pandemic just reinforced that.”

Tesla shares closed down 3.8% on Friday, but have been on a spectacular run this year despite the global coronavirus pandemic and the onset of a recession. 

Apple is now the world’s most valuable publicly traded company – The Verge

Apple is now the world’s most valuable publicly traded company, passing Saudi Arabia’s state-owned oil company Saudi Aramco. As of close of business Friday, Apple has a market valuation of $1.84 trillion, while Saudi Aramco’s is $1.76 trillion, according to CNBC. Apple’s stock, which has been on a largely-steady climb since the end of March, closed up more than 10 percent on Friday following the company’s record-breaking third-quarter earnings on Thursday, ending the day at $425.04.

Apple’s total revenue for Q3 hit $59.7 billion, up 11 percent from last year. Strong Mac and iPad sales were a highlight, and the company likely saw increased demand for the devices while people have been sheltering in place due to the COVID-19 pandemic. Apple also announced a four-for-one stock split as part of its third quarter earnings, which will lower the price of an individual stock.

Amazon, Facebook, and Google all announced earnings yesterday as well, and for the most part, they had pretty good quarters. Amazon doubled its profit — during a pandemic. Facebook saw a daily user increase of 12 percent year over year to 1.79 billion. And combined, the four companies netted $28.6 billion in profits. As my colleague Liz Lopatto put it, during the pandemic, the tech companies are raking it in.

50 Percent of ‘Very Liberal’ Americans Say Trump Donors Should Be Fired from Jobs

50 Percent of ‘Very Liberal’ Americans Say Trump Donors Should Be Fired from Jobs


Exactly half of Americans who describe themselves as “very liberal” say a business executive who donates his or her own money to President Trump’s re-election campaign should be fired, according to a new survey.

The CATO/YouGov poll asked all Americans if business executives who donate private money to Trump should be canned. Liberals were the most likely to say “yes.”

Although 43 percent of liberals said a business executive who donated to Trump should be fired, the number jumped to 50 percent among Americans who self-label as “very liberal.”

Around a third of moderates (32 percent) said an executive should be fired for donating to Trump. Among all Americans, 31 percent backed such an action.

Among age groups, adults under 30 were most likely (44 percent) to say an executive should be fired.

“These results are particularly notable given that most personal campaign contributions to political candidates are public knowledge and can easily be found online,” Cato’s Emily Ekins wrote in an analysis.

Elizabeth Nolan Brown of Reason.com called it a “disturbingly high percentage” of people who support a loss of job for political donations.

Meanwhile, support for firing business executives over donations to Democrat Joe Biden was not as high, with 22 percent of all Americans – nine percentage points less than that of Trump – saying a business executive who…

… Read More

Click here to read the rest of the story from our content source/partners – Christian Headlines.

قالب وردپرس